Bricks vs clicks: The case for an online sales tax
Article
It's time to rethink how we tax retail.
The high street is being taxed too much
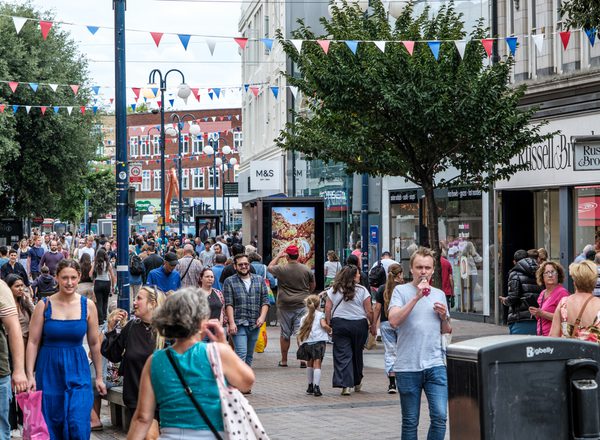
The high street is not just a collection of shops, it is shared economic and social infrastructure where people can work, meet, access services and spend leisure time. The closure of a high street business is felt deeply by local communities. It lowers footfall which weakens neighbouring businesses, and, importantly, boarded up premises become a visible symbol of social decline felt across the country.
Britain’s business tax system was designed for an economy where commercial property was closely tied to economic activity: when shops were where businesses generated their sales and profits. That relationship has weakened in the contemporary economy where nearly three in ten retail sales are now made online, allowing businesses to generate substantial revenues with a much smaller physical footprint.
The result is a growing mismatch between how businesses generate sales and the tax bases on which businesses are taxed.
Case study for a lopsided business tax system
Next’s financial accounts illustrate the differences in selling online and in stores. Comparing two channels within the same business avoids turning this into a comparison between large online retailers and smaller high-street firms. Amazon and a family business on the high street have many other economic differences that confound the analysis.
In the year ending January 2026, Next’s UK online operation had a profit margin of 18.5 per cent compared to a margin of 10.2 per cent in stores. In other words, its online profit margin was around 80 per cent higher than for stores. This cannot be attributed solely to business rates, as product mix and other operating costs also affect profitability, but highlight the structural differences between both modes of selling.
International comparisons support the argument that the UK is unusually reliant on property taxation. Property taxes generated 10.5 per cent of UK tax revenue, compared to an OECD average of 5.1 per cent. Commercial property is a significant part of that picture – in 2026, business rates raised £27.6B, or 3 per cent of all UK tax revenue and 28 per cent of UK property tax take.*
A possible reaction to this might be to increase taxes on warehouses. But this would reinforce existing reliance on property and penalise the infrastructure used by both online and high street retailers. Instead, the tax system must shift the burden away from premises and towards economic activity.
A carefully designed online sales tax, with the proceeds used to reduce business rates, would begin to rebalance the tax system while wider reform is developed.
A high share of revenue from property taxes is not necessarily a problem, particularly in a country with substantial wealth held in property it can be the right and economically efficient form of tax. But there is an important distinction between taxing property ownership and taxing the buildings businesses use to operate. Taxing land values and returns from property ownership can capture wealth without discouraging productive investment. By contrast, taxing businesses for occupying and investing in buildings can discourage investment. Given the UK’s reliance on property taxation, getting this right is particularly important.
Ultimately, this should be achieved via reforming business rates. However, it is complex and would require significant changes to the wider architecture of local government finance, as business rates are an important source of revenue for councils.
There is an important distinction between taxing property ownership and taxing the buildings businesses use to operate
We therefore propose a more near-term solution: an online sales tax (OST), matched by a reduction in high street business rates, to level the playing field between online and bricks and mortar retailers.
An online sales tax can level the playing field
An OST should apply to businesses’ remote sales of goods to consumers, with revenues used to fund targeted reductions in business rates for high street businesses. The tax would apply at a rate of 2 per cent on remote sales, with a reduced rate of 1 per cent for click-and-collect purchases, recognising they generate footfall for physical stores. Depending on the final design (see below), this could raise around £1.5 billion.
The tax should be applied to purchases of goods made without visiting a physical store, whether online, by telephone or through another remote channel
The tax should be applied to purchases of goods made without visiting a physical store, whether online, by telephone or through another remote channel. This is clearer than trying to define an “online sale” and reduces opportunities for businesses to avoid the tax by shifting customers between sales channels.
This tax should be levied on business’ remote sales at the end of the accounting year rather than individual sales, avoiding the visibility of the tax upon checkout. Businesses should calculate and pay their liability as part of their existing tax returns.
Key design features include:
- an exemption for smaller businesses, with no tax due on the first £500,000 in annual remote sales, ensuring the tax is concentrated on larger retailers without creating a cliff edge
- responsibility for large marketplaces to collect the tax on transactions made on their platforms, including sales by smaller traders
- consider exempting goods that are zero-rated for VAT, including most groceries, to protect household budgets and avoid introducing a separate definition of essential goods.
An important consideration is the impact OST might have on the cost of living, which is dependent on how much of the tax businesses pass on to consumers through higher prices.
Even relatively small increases matter more for goods that make up a significant share of household budgets
Questions on how OST could impact prices makes the treatment of essential goods particularly important. Even relatively small increases matter more for goods that make up a significant share of household budgets, particularly for low-income households. Exempting goods that are already zero-rated for VAT, including most groceries, limits the risk while using an established definition of essential goods.
Most important in the design is an inherent trade-off between the revenue collected from OST and protecting the most vulnerable firms and consumers, which the design features above address.
Use the revenue to cut business rates
Tax revenue should be used to fund permanent business rate reductions for businesses that drive footfall on high streets. Andy Burnham’s proposal to provide additional relief only for pubs and live music venues is a positive first step, but this would exclude other businesses facing similar challenges. Announcing the OST at the budget alongside broader business rates cuts would provide a clear and visible package of support for the high street.
The government should use OST revenue to cut business rates bills for retail, hospitality and leisure (RHL) businesses, in addition to the announced 20 per cent cut for pubs, clubs and live music venues. This can be achieved by lowering the business rates multiplier, the tax rate used to calculate a property’s business rates bill. Given that smaller businesses are less able to absorb fixed property costs, a larger reduction should be given for smaller properties.
| Business rates category | Current multiplier | Proposed multiplier | Cost | Annual average saving per eligible property |
|---|---|---|---|---|
| Small RHL | 38.2 | 28.2 | £707m | £1,400 |
| Standard RHL | 43p | 41p | £189m | £2,500 |
Calculated using data from MHCLG.
The total cost of this package would be around £900 million. There are two important considerations.
- Business rates are a significant source of funding for local government, so central government should fully compensate local authorities for any reduction in business rates. OST revenues should be hypothecated for this purpose so that support reaches businesses without impacting local government funding.
- Business rates are devolved to Scotland and Wales, so the £900 million cost estimate only applies to England. Since an OST would be collected across the UK, revenues should be shared with devolved governments on the same basis and used to fund equivalent business support where appropriate.
An objection to business rate cuts is that they ultimately become a subsidy for landlords. Rents are constantly renegotiated between landlords and commercial tenants, and there is risk that slowly rents will adjust upwards to absorb some of the reduction in businesses’ tax bills.
However, this effect depends on the nature of the local property market. If demand for commercial space is strong and there is limited supply, landlords can raise rents and are able to capture the benefit of business rates cuts. In high streets with high vacancy rates, commercial tenants have much more bargaining power, and rate cuts could make bricks and mortar ownership more attainable. This could increase occupancy and bring more business to the high street.
Supporting the high street is not at odds with technological change and does not work against consumer preferences to shop online
A tax system for the economy we have
Supporting the high street is not at odds with technological change and does not work against consumer preferences to shop online. The problem is not that online retail has grown, but that the tax system has failed to adapt alongside it. Businesses no longer need the same physical footprint to generate sales, and the value of commercial property is an increasingly weaker proxy for economic activity. While broader reform of business rates will take time, an online sales tax offers a practical first step, shifting some of the tax burden away from commercial property and towards the sales businesses generate.
Notes
* Calculated by multiplying UK total tax revenue (£937.8 billion) by 10.5 per cent (OECD Revenue Statistics 2025) to approximate UK property tax take as 98.5 billion.
Related items
Beyond boom and bust: The supply case for social housing
How the government can use social housing to unlock housing supply and demand.
Bottleneck Britain: How digital competition could power UK growth and sovereignty
Artificial intelligence could be the UK’s biggest economic opportunity in a generation, but only if its gains are spread across the economy rather than pooled within a handful of companies.
Beyond headroom: Why we need a better fiscal framework to fix the UK’s long term problems
There has been long-standing debate about the UK’s fiscal rules and fiscal framework.